Simple Checkbook Ledger
Teelu Apps
- 3.4
- 1.24K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
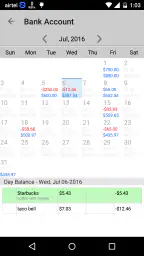
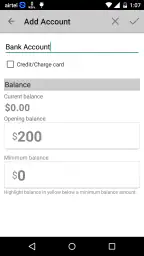
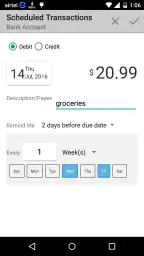
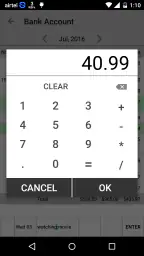
Simple Checkbook Ledger Pros and Cons
Pros
- Simple layout makes daily income and expense entries quick.
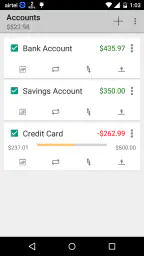
- Supports multiple accounts for separating personal and household finances.
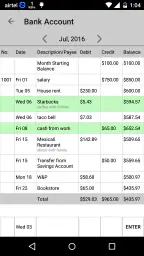
- Running balances help track available funds after every transaction.
- Useful search and filtering tools make past entries easy to find.
- Works well for users who prefer manual control over automated budgeting.
Cons
- Manual entry can become time-consuming for users with many transactions.
- Limited automation may require frequent updates to keep balances accurate.
- The interface may feel dated compared with newer finance apps.
- Advanced budgeting and spending-analysis features are relatively limited.
- Users should verify backup options before relying on it for important records.
 Analysis by All-app
Keeping a clear record of everyday spending sounds simple until receipts pile up, payments are made from different accounts, and the balance in your head stops matching the balance at the bank. Simple Checkbook Ledger takes a deliberately focused approach to that problem. It is a finance app from Teelu Apps built around recording account activity in a checkbook-style ledger rather than trying to become a complete banking platform.
I found that focus useful. Instead of asking me to connect every financial service or learn a large budgeting system, it gives me a place to enter money in and money out, review the running balance, and keep personal records organized. The trade-off is equally clear: this is most comfortable for people who are willing to maintain their own ledger. If you want automatic transaction imports, investment analysis, bill negotiation, or a full household budget dashboard, you will probably feel its limits quickly.
The app is free to install, with optional in-app purchases priced at $1.99 per item. It is suitable for Everyone, runs on devices using at least iOS 11, and its current version is 3.5. Teelu Apps released it on Aug 3, 2016, so its basic checkbook identity feels intentional rather than like a small part of a much larger financial suite.
How I use the ledger from the first entry onward
I’d begin by treating the opening balance as the ledger’s anchor: check it against the account you intend to track, then enter one recent transaction and see whether the resulting total makes sense. That small test can catch a setup slip before it spreads across later entries. From there, the key is choosing a simple routine that makes each new record easy to recognize and review.
A practical starting point for account tracking
The most important decision is to treat the ledger as a record of completed or planned account activity, not as a magical view of your finances. I would begin by creating or selecting the account I want to monitor, then enter the current balance carefully. That opening figure matters because every later entry depends on it. A small mistake at the beginning can make the running total look wrong even when every later transaction is accurate.
From there, the everyday workflow is straightforward: record income when it arrives, enter purchases as they happen, and use the balance as a working estimate of what remains. The checkbook format is especially comfortable for people who still think in terms of deposits, withdrawals, and a running total. It also suits a separate spending account, a shared household account, or a cash record where automatic bank synchronization would not help anyway.
My strongest advice is to enter transactions at the moment they become relevant. Waiting until the end of the week creates a memory exercise, and small purchases are exactly the ones most likely to disappear from memory. A quick entry after buying lunch or paying for transport is more reliable than trying to reconstruct the day from scattered receipts.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
There is also a useful distinction between the balance shown in the ledger and the balance a bank may display. A payment can be recorded in your personal record before it clears, while a deposit can appear in an account before you have written it down. I would use the app as a deliberate personal register, then reconcile it against the actual account periodically. That habit prevents a common mistake: assuming that a neat ledger is automatically a live bank balance.
A realistic everyday routine
Imagine using one account for rent, groceries, subscriptions, and occasional cash withdrawals. On payday, I would enter the deposit, then add the regular bills as they leave the account. During the week, I would record smaller purchases immediately rather than grouping them under a vague “miscellaneous” amount. Before making a larger purchase, I could check the running balance and see the effect of the transactions already entered.
That routine is not glamorous, but it is valuable because it turns vague awareness into a sequence of decisions. If the balance looks lower than expected, I can inspect the recent entries instead of guessing. If a payment has been forgotten, the missing record becomes easier to spot during reconciliation. The app works best when it becomes a short daily habit, not something opened only after finances are already confusing.
One non-obvious benefit of this approach is that it can cover money that never passes through a connected bank account. Cash spending, reimbursements, and informal transfers can be recorded alongside ordinary account activity if I choose a consistent method. That makes the ledger more flexible than a bank-only tracker, although it also means the accuracy depends on my discipline.
Where the simple design helps
The app’s simplicity lowers the mental cost of recording a transaction. A large financial platform may offer charts, goals, credit monitoring, and account connections, but those extras can make a single cash purchase feel like an administrative task. A ledger is easier to understand: money comes in, money goes out, and the balance changes.
That clarity is useful for someone learning to manage a first account, a person who wants a private manual record, or a user who prefers not to connect financial credentials to another service. It can also be a good companion to a spreadsheet when I want a quick mobile entry point rather than a full table of formulas.
Still, I would not confuse a clean workflow with a complete financial plan. The ledger tells me what I recorded and how those entries affect the total. It does not replace the judgment needed to decide whether spending is affordable, whether a recurring bill should be canceled, or whether several accounts need a coordinated plan.
Settings that deserve attention before daily use
Experienced use begins with checking the app’s available account and transaction settings instead of accepting every default. I would look first at how accounts are named and organized. Clear names such as “daily spending,” “household,” or “cash” make later review much easier than generic labels. If the app lets me choose transaction details, I would keep the structure consistent so similar payments can be recognized quickly.
I would also review any options related to the way balances and entries are displayed. A ledger is easier to audit when dates, amounts, and descriptions are presented in a predictable order. The exact preference matters less than choosing one arrangement and sticking with it. Constantly changing how entries are viewed can make a familiar account feel less familiar when I need to check it quickly.
Because the app is manual, I would pay particular attention to settings that affect the entry process rather than searching for automation that the product is not designed to provide. The best configuration is the one that makes a normal transaction take as few decisions as possible. If I hesitate over categories, descriptions, or account selection every time, I am more likely to postpone recording the purchase.
Another setting-related habit is to decide how I will handle pending payments. I prefer a clear personal rule: record an outgoing payment when I commit to it, then reconcile the account when it clears. Someone else may prefer to wait until the bank confirms the transaction. Either method can work, but mixing them produces misleading balances. Simple Checkbook Ledger rewards consistency more than complexity.
Settings are only useful when they support review
I would not spend time customizing the ledger merely to make it look tidy. The practical test is whether a setting helps answer a real question: What did I spend? Which account changed? Did I already record that payment? Is the current total believable? If a preference does not improve one of those checks, it is probably not worth making the workflow slower.
For a shared household, this becomes even more important. If two people record activity, both should agree on naming, timing, and the treatment of transfers. Otherwise, one person may record a transfer as an expense while the other records it as income, creating a distorted picture. The app can hold the entries, but the household still needs a shared bookkeeping rule.
The same principle applies when tracking cash. I would avoid treating every cash withdrawal as the final expense if I intend to record the later purchases individually. Instead, I would choose whether the withdrawal represents money moved into a cash account or money already spent. Recording both the withdrawal and the purchases as expenses would count the same money twice.
Faster patterns for people who keep the ledger current
The fastest users are not necessarily the ones who type quickly. They are the ones who remove uncertainty from repeated actions. I would create a small routine around the transactions I make often: record the amount, use a short but recognizable description, and check the resulting balance before closing the entry. Repetition makes this process quicker without requiring invented shortcuts or complicated setup.
For recurring bills, I would use a calendar reminder outside the ledger if I need a prompt, then enter the transaction in the app when it is due or when I decide to treat it as pending. This separates two jobs that are easy to confuse: remembering that a payment exists and recording what it did to the account. A ledger can document the payment, but a reminder system is better suited to making sure I do not forget it.
Another efficient pattern is a short reconciliation session rather than constant perfection. I might record everyday purchases immediately, then compare the ledger with the account statement at a regular point in the week. During that check, I would look for duplicates, missing entries, and amounts that differ. This catches errors while they are still easy to remember.
Descriptions should be brief but useful. “Store” may be too vague months later, while a short description that identifies the purpose gives me something to search visually during review. I would avoid writing long notes for every transaction because that turns a quick ledger into a diary. The right amount of detail is enough to recognize the payment without slowing down entry.
A particularly useful trade-off appears with small purchases. Recording every minor expense gives the most accurate balance, but it can feel tedious. Grouping them is faster, yet it hides where the money went and makes reconciliation harder. I would record individual purchases when I am trying to understand spending habits, and use a consistent grouped entry only when precision is less important than speed.
Using the app alongside, not instead of, other tools
Compared with a paper checkbook, the app is easier to carry and revise. A mistaken entry can be corrected without crossing out a page, and the running balance is more convenient than doing arithmetic by hand. Compared with a spreadsheet, it should feel less like maintaining a document, although a spreadsheet remains stronger for custom formulas, detailed categories, and long-term analysis.
Compared with automatic budgeting apps, the difference is more fundamental. Those services can reduce manual work by importing activity and may offer broader spending reports. Simple Checkbook Ledger gives me more direct control over what enters the record, which can be preferable for privacy-conscious users or accounts that do not connect cleanly. The price of that control is that I must supply the information myself.
I would use it with a bank app rather than expecting it to replace one. The bank app is the authority for cleared transactions and available funds. This ledger is better for personal organization, planned entries, cash activity, and a running record shaped around my own habits. Keeping those roles separate makes the app more useful and reduces the risk of acting on an outdated manual balance.
What advanced users should understand about the limits
The app’s main limitation is not that the ledger is too simple; it is that manual tracking has a ceiling. A person with several accounts, frequent card payments, transfers, reimbursements, and shared finances may spend more time maintaining records than learning from them. In that situation, an automated finance service or a carefully designed spreadsheet may be the better primary tool.
I would also be cautious about using a manual ledger for decisions that require current account information. Before a large payment, I would verify the actual bank balance separately. The app can help me remember obligations and see my recorded commitments, but it should not be treated as a real-time authorization source.
Another limitation is analytical depth. A checkbook record can show activity clearly, but it is not the same as a detailed budget with flexible categories, trend comparisons, or forecasting. If my main goal is to reduce restaurant spending or compare monthly household costs, I may need another method for analysis. The ledger can provide the raw record, but I would not choose it solely for visual reports.
Security habits matter too. Since the usefulness of a manual finance app depends on the reliability of its record, I would avoid entering sensitive details that are unnecessary for identifying a transaction. I would also keep the device protected and maintain whatever backup or export routine the app supports if the information is important to me. A financial record is only helpful when it remains available and trustworthy.
The optional purchases should also be considered in context. The free starting point makes it easy to test the workflow before committing to it, while the $1.99 per-item purchase model means I would check what each optional item changes before buying. I would not pay simply because I felt I needed more features; I would first confirm that the added capability solves a problem I actually encounter.
Who will appreciate it, and who should skip it
I think Simple Checkbook Ledger is a good fit for someone who wants a focused manual account register, prefers entering transactions personally, and values a straightforward running balance over an elaborate financial dashboard. It is also sensible for cash tracking, a single spending account, or a user who wants a separate record without linking every financial service.
It may suit a beginner because the checkbook idea is easy to explain: start with a balance, record changes, and review the result. However, beginners still need to learn reconciliation and consistent entry habits. The app can make bookkeeping less intimidating, but it cannot make inaccurate input accurate.
I would skip it as a main finance tool if automatic synchronization is essential, if I need sophisticated category analysis, or if I manage a complicated collection of accounts and investments. I would also look elsewhere if I tend to forget manual entries, because that weakness will show up directly in the balance. In those cases, the convenience of an automated alternative is likely worth more than the control of a simple ledger.
My final view after settling into the routine
Simple Checkbook Ledger earns its place by staying close to one useful job: keeping a personal checkbook-style record. Its average rating is 3.4 from around 2.5 thousand ratings, and more than 100 thousand installs show that the format has found a real audience. Those figures do not change the central question, though: am I willing to enter and review my own transactions?
For me, the answer is yes when I want a lightweight register that sits alongside my bank account. The app is clearest when I use it deliberately: set a reliable opening balance, record activity promptly, separate pending entries from cleared transactions according to one rule, and reconcile regularly. Those habits matter more than decorative customization or trying to force the app into the role of a full budgeting platform.
My recommendation is simple: choose it if you want a focused manual ledger and appreciate seeing the direct effect of each entry. Choose a different finance solution if your priority is automation, deep reporting, or a complete view of multiple financial products. In the right situation, this modest approach is a strength. It gives me fewer distractions and a record I can understand at a glance, provided I am prepared to keep that record honest.
After using it that way, I see the app less as a replacement for modern banking tools and more as a dependable personal bookkeeping surface. That distinction is important. It will not do the thinking for me, but it can make the thinking clearer—and for everyday account control, that is often exactly what I need.
Frequently Asked Questions
What is Simple Checkbook Ledger used for?
Simple Checkbook Ledger is designed to help you record and monitor personal financial transactions in a straightforward way. You can enter deposits, withdrawals, payments, and other adjustments, then review your running balance and transaction history. It is useful for people who want a simple alternative to a full-featured budgeting app or online banking dashboard.
Is Simple Checkbook Ledger suitable for detailed budgeting?
The app is primarily focused on checkbook-style transaction tracking rather than comprehensive financial planning. It can help you understand where your account balance stands and maintain an organized record of spending, but it may not include advanced tools such as automatic bank synchronization, investment tracking, debt planning, or category-based budgeting. Users seeking a complete household budget should check the available features first.
Does Simple Checkbook Ledger connect directly to my bank account?
Simple Checkbook Ledger is generally intended for manually recording financial activity instead of replacing your bank’s official application. Before downloading, review its current permissions and feature description to confirm whether bank connectivity or importing transactions is supported on your device. Manual entry can offer greater control and privacy, but it requires you to keep the ledger updated whenever money moves.
Can I use Simple Checkbook Ledger on Android and iOS?
Availability can vary depending on the developer, region, and store listing, so users should verify whether Simple Checkbook Ledger is offered for their specific Android or iOS device. Also check the minimum operating-system version, recent update date, and compatibility information before installing. These details are especially important if you use an older phone or tablet.
Is my financial information safe in Simple Checkbook Ledger?
Because a checkbook ledger may contain balances, payment details, and personal notes, privacy should be considered before entering sensitive information. Read the app’s privacy policy, examine requested permissions, and determine whether data is stored locally, backed up, or shared with third parties. Avoid entering complete banking passwords, card PINs, or other credentials unless the developer clearly explains secure handling.